

Trump Accounts: Official App analysis by Appwee
I approached Trump Accounts: Official App as a decision tool rather than something to open every day for entertainment. It is a free finance app from the Department of the Treasury, built around the idea of investing in a child’s future. That purpose makes the right question less about how many screens it has and more about whether it helps your family understand, organize, and act on this specific kind of account.
My first impression is that the app has a very focused identity. It is not trying to replace a full banking app, a budgeting package, or a general investment platform. That focus is useful if you are looking for information and account-related guidance in one official place. It is less compelling if you want broad control over everyday money, detailed portfolio analysis, or a single app that manages every financial goal in your household.
How I Would Decide Whether It Fits
Start with the family task, not the download
Before installing it, I would define what I actually need to do. If the goal is to understand Trump Accounts, check the relevant process, or keep child-focused investing information separate from ordinary household spending, this app deserves a look. If the goal is to compare many investment products, track unrelated accounts, or build a complete financial plan, I would treat it as one piece of the process rather than the whole solution.
That distinction matters because finance apps often look similar in an app store while serving very different jobs. A bank app is usually centered on transactions. A budgeting app is centered on spending patterns. A brokerage app is centered on investment decisions and account activity. This product sits in a narrower space: it is aimed at a child’s future and the Trump Accounts subject specifically. I found that specialization more helpful than a crowded menu would have been.
The audience is also important. Parents and guardians who want a straightforward starting point may appreciate the official source. Relatives who are considering a contribution or simply want to understand how the account fits into a child’s long-term plans may also find the focused approach useful. On the other hand, an experienced investor who wants advanced research tools will probably reach the limits of this app quickly and should keep a separate investment service available.
What the store signals about the experience
The app is rated for Everyone, which makes sense for a public-facing finance resource that may be used by families with different levels of financial experience. Its current version is 2026.34.0, and it requires Android 7.0 or later. Those details are practical rather than glamorous, but they matter when a parent is using an older phone or when several family members need access from different devices.
Its reception is encouraging: it holds a 4.8 average from around 3.1 thousand ratings, with roughly 453 written reviews. It has also passed the 500-thousand-install mark. I would not treat those figures as proof that every household will enjoy the workflow, but they do suggest that the app has attracted meaningful interest and that many users have found it useful enough to rate.
Because it is free, the initial decision is relatively easy. You are not committing money just to test the interface. The more important cost is attention: you still need to read carefully, keep your child’s information organized, and avoid assuming that an official app automatically answers every personal financial question.
My practical test for a first session
In a first session, I would look for three things. First, can I quickly understand what the app is asking me to do? Second, can I distinguish general educational material from information that applies to my own child or account? Third, can I leave the app knowing what my next real-world step is?
That third test is easy to overlook. A finance app can be polished and still leave users unsure whether they should gather documents, contact another organization, speak with a tax professional, or simply wait. For this product, I would keep a small note beside me with the child’s basic details, questions, and any follow-up tasks. That turns the app from a passive reading experience into a checklist for a family decision.
Where the focused design helps
The strongest reason to choose this app is authority of purpose. Since the developer is the Department of the Treasury, I would begin here when I want information connected to the government’s own Trump Accounts program rather than relying on a social-media explanation, a general finance blog, or a sales page from a private provider.
That does not mean I would stop checking every important detail. Official information can still require careful reading, especially when a rule affects eligibility, timing, contributions, or a child’s future. What the app gives me is a better starting point for separating program information from speculation. In a subject where families may hear conflicting summaries, that is a real advantage.
I also like the narrow audience. The phrase “invest in your child’s future” is not just a slogan in this context; it tells me how to judge the app. The useful question is whether the information helps me make a patient, long-term decision for a child, not whether it offers the excitement of active trading. For a parent who wants to establish a dedicated financial habit, that framing can reduce distractions.
A second strength is the possibility of using the app during a family conversation. I would not hand a child a complicated brokerage dashboard and expect them to understand it. Instead, I could use the app to explain why a child-focused account is being considered, what questions the adults still need to answer, and why long-term investing is different from spending money today. The app’s subject gives that conversation a concrete anchor.
Three useful habits that make it more valuable
My first tip is to use it as a verification checkpoint. If a relative sends you a message describing Trump Accounts, compare the claim with what the official app says before acting. This is especially useful when the message contains urgent language or asks you to provide sensitive information elsewhere. The app should not replace caution, but it can help you identify when a claim deserves a closer look.
My second tip is to separate questions into “understand now” and “decide later.” For example, I would first clarify the account’s purpose and the steps involved. Only after that would I discuss how it fits with emergency savings, education costs, retirement planning, or other family priorities. This prevents the common mistake of treating a child’s investment account as a substitute for basic household financial stability.
My third tip is to revisit the app with the same written questions instead of browsing randomly. On the first visit, I might ask what the account is, who needs to act, and what information I should prepare. On a later visit, I could check whether those questions have changed after speaking with a financial professional or another responsible adult. This makes it easier to notice what has been answered and what still needs outside guidance.
A fourth practical use is preparing for a conversation with a bank, tax adviser, or investment professional. I would record the exact points I want clarified and bring them along. That is more efficient than opening several unrelated apps and trying to reconstruct the program from memory. The official app becomes the reference point, while the professional conversation handles personal circumstances the app cannot evaluate for me.
Where a different kind of app may fit better
The main limitation is the same feature that makes this app appealing: its narrow scope. If I want one place to see checking activity, credit cards, bills, savings goals, and investments, I would choose a household finance app or my bank’s app instead. Those tools are better suited to a daily money routine because they show the broader picture of cash flow.
If I already use a brokerage platform, I would keep using it for investment research, portfolio views, and broader account management when those tasks are available there. Trump Accounts: Official App should not be judged as a replacement for every brokerage feature. Its value is in the specific account topic and official context, not in competing with a full investment workstation.
A budgeting app may also be the better choice for a family that is still trying to stop overspending or build an emergency reserve. Long-term investing for a child is meaningful, but it should not make the household’s short-term finances fragile. I would rather use a budgeting tool to create breathing room first and then use this app to investigate the child-focused account with a clearer understanding of what the family can responsibly commit.
There is another situation where I would slow down: families with complicated tax, custody, or financial arrangements. An official app can explain a program, but personal circumstances may affect how its information applies to you. In that case, I would use the app to prepare questions, not to make a major decision based on a quick interpretation of one screen.
The trade-off between simplicity and control
Choosing this app means accepting a trade-off. A focused official tool may be easier to approach than a general investment platform, but it may not provide the same breadth of analysis or customization. That is not necessarily a flaw. For a first-time parent, fewer distractions can be a benefit. For a confident investor, fewer controls can feel restrictive.
I would also avoid confusing an official source with personalized advice. The app can help me understand the subject and organize my next steps, but it cannot know my complete family budget, risk tolerance, other investments, or long-term plans unless those details are properly part of the service. I would keep that boundary clear, particularly when discussing money intended for a child.
What switching really costs
Moving from scattered web searches or informal advice to this app should be relatively easy because the app is free. The harder part is changing the way I work. I would need to stop copying fragments of information into different notes, identify which source is official, and build a repeatable process around the account.
Moving from a general finance app is different. I would not abandon the budgeting or banking tool that already shows my household’s full financial picture. Instead, I would use this app alongside it. The cost of switching is lowest when I treat the product as a dedicated reference and planning companion rather than trying to force it into a role it was not designed to fill.
Families should also think about continuity. If several adults share responsibility for a child’s finances, agree on where you keep questions and follow-up notes. Otherwise, one person may read the app, another may rely on an old message, and a third may assume an action has already been completed. A simple shared checklist can prevent that confusion without turning the process into a complicated project.
On an older Android phone, the minimum operating-system requirement is worth checking before planning around the app. If a family member cannot install it, the practical alternative is not necessarily another finance app; it may be using the official information through another available channel and keeping the same careful question-and-verification process.
My recommendation for different users
I recommend Trump Accounts: Official App to parents, guardians, and relatives who want a clear official starting point for understanding Trump Accounts and considering how they fit into a child’s future. The free price removes a common barrier to trying it, and the strong 4.8 average suggests that many users have responded well to the experience.
I would especially recommend it to someone who feels overwhelmed by conflicting explanations online. Start with one child, one set of questions, and one written list of next steps. Do not rush to make the account the center of the household’s financial plan. Use it to become informed, then compare the information with your family’s actual priorities.
I would not recommend relying on it alone if you need comprehensive budgeting, everyday banking, advanced investment research, or personalized financial planning. In those cases, keep the app as a focused official reference while using the category of tool that handles the larger job better.
My final view is positive but measured. This app is most useful when you treat it as a trustworthy starting point for a specific family decision, not as a complete financial command center. Its narrow subject is its clearest advantage, and also its main boundary. For the right user, that focus can make a complicated conversation easier to begin; for everyone else, a broader finance or investment app may deserve the leading role.
Gallery
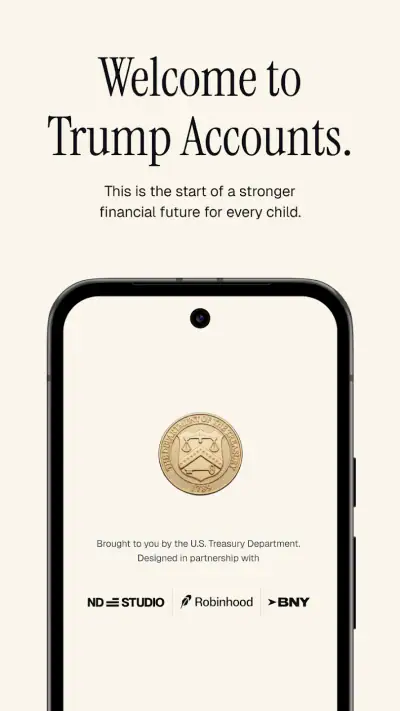
Trump Accounts: Official App Pros and Cons
- Official source for managing eligible Trump Accounts
- Clear account information and enrollment guidance
- Useful updates on program rules and deadlines
- Accessible from compatible Android and iOS devices
- Helps families understand available account benefits
- Eligibility may be limited by age
- citizenship
- or other requirements
- Some features may require identity or eligibility verification
- Program details and benefits could change with new legislation
- The app may offer limited functionality outside the United States
- Personal and family information requires careful privacy review
Trump Accounts: Official App Frequently Asked Questions
What is the Trump Accounts official app used for?
The Trump Accounts official app is designed to provide information and access to the Trump Accounts program, including eligibility details, enrollment guidance, contribution rules, and account-related updates. Before downloading, users should confirm that they are using the legitimate application or official government-linked service, because similarly named apps or websites may not be affiliated with the program and could request sensitive personal information.
Who may be eligible to open or benefit from a Trump Account?
Eligibility depends on the current rules of the Trump Accounts program, including requirements related to the child’s age, citizenship or residency status, birth date, and the identity of the parent or authorized representative applying. The app may explain these conditions, but users should review the latest official guidance carefully because program requirements, qualifying dates, and enrollment procedures can change over time.
What personal information is required when using the app?
Depending on the feature being used, the app may request information such as a user’s name, date of birth, address, contact details, tax-related information, or details about an eligible child. Some services may also require identity verification. Only enter information after checking the developer, privacy policy, and secure connection. Never share passwords, verification codes, or financial details through unofficial links or messages.
Does the app allow users to manage contributions and account activity?
The available account-management features depend on how the official service is implemented and whether the app connects directly to an account provider or mainly offers program information. Users should look for clearly explained options for viewing balances, checking contributions, updating contact details, or receiving notifications. Any limits, processing times, fees, and investment-related conditions should be confirmed in the official terms before making decisions.
Is the Trump Accounts app free, safe, and available on every device?
Downloading an official government-related app should generally not require a separate purchase, although account services may involve rules or costs explained by the program administrator. Availability can vary by country, operating system, and device version. Before installing, check the publisher name, download count, recent reviews, permissions, update history, and official links. Avoid unofficial APK files or apps requesting unnecessary access to your device.














